
Reverse Mortgage Obligations for Heirs: Estate Settlement Guide
Understand reverse mortgage obligations for heirs and estate settlement, from non-recourse protection to repayment options, so you can settle the estate with confidence.
By Alice Ellis
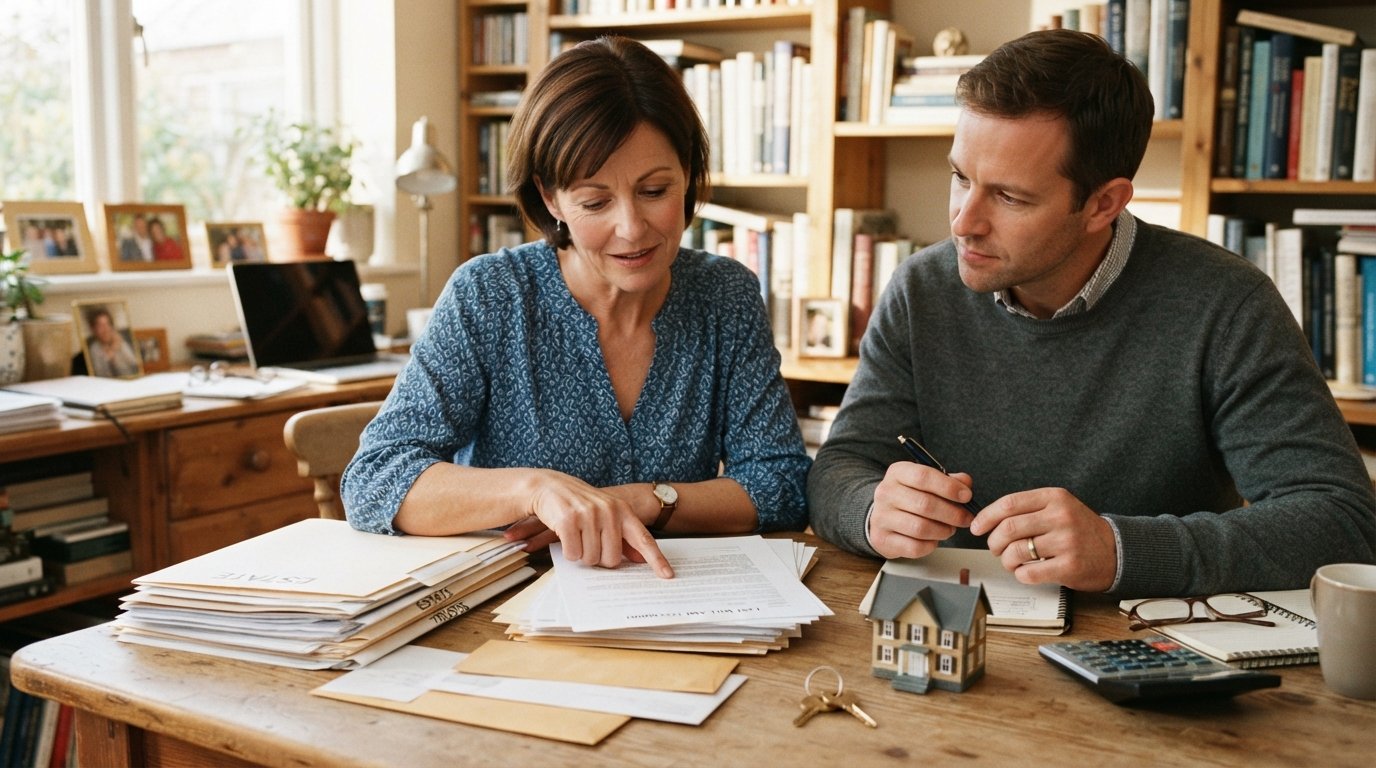
When a parent or loved one passes away with a reverse mortgage on their home, the last thing you need is financial uncertainty. Yet that is exactly what many heirs face: a confusing letter from a servicer, a ticking clock, and a tangle of rules that seem designed to trip you up. The good news is that reverse mortgage obligations for heirs and estate settlement are more manageable than they appear, provided you understand the non-recourse protection, the deadlines, and the options available to you. This guide walks you through every step, from the first notification to the final closing, so you can settle the estate with confidence and avoid costly mistakes.
Understanding the Non-Recourse Feature: Your First Line of Defense
The single most important concept for heirs to grasp is that most reverse mortgages are non-recourse loans. That means the lender can only look to the home for repayment, not to the heirs' personal assets. If the home sells for less than the loan balance, the lender generally absorbs the difference (subject to certain conditions). This protection is a cornerstone of the Home Equity Conversion Mortgage (HECM) program, which is the most common type of reverse mortgage and is insured by the Federal Housing Administration (FHA).
However, non-recourse protection is not automatic in every situation. Heirs must follow specific procedures and meet deadlines to preserve it. For example, if the heirs fail to respond to the servicer within the required time frame, the servicer may initiate foreclosure, and the non-recourse shield could be lost. Additionally, if the heirs choose to keep the home and refinance the reverse mortgage into a new forward loan, the non-recourse feature does not apply to the new loan. Understanding these nuances is critical before making any decisions.
For a deeper dive into how estate planning interacts with reverse mortgages, including strategies to avoid probate delays, see our guide on estate planning considerations with a reverse mortgage. It covers trusts, wills, and the importance of clear beneficiary designations.
Immediate Steps for Heirs After a Borrower's Death
The clock starts ticking as soon as the borrower passes away. While there is no need to panic, acting promptly can prevent unnecessary stress and preserve your options. The first step is to notify the reverse mortgage servicer. You can find the servicer's contact information on the monthly statement or by contacting the lender directly. When you call, have the borrower's loan number, Social Security number, and a copy of the death certificate ready. The servicer will guide you through the next steps and may send a formal package of documents to complete.
Within 30 days of the borrower's death, the servicer typically requires written notification. After that, you will need to provide documentation to establish your authority to act on behalf of the estate (such as letters testamentary or letters of administration) and to confirm the property's occupancy status. The servicer will then issue a formal notice that outlines the repayment options and the deadlines you must meet.
Here is a checklist of immediate actions to take:
- Obtain multiple certified copies of the death certificate.
- Locate the reverse mortgage statement and identify the servicer.
- Notify the servicer by phone and follow up in writing.
- Gather estate documents (will, trust, letters of administration).
- Secure the property and maintain insurance coverage.
Keep in mind that during this initial period, the servicer may not accept payments from the estate unless authorized. Do not send payments without confirming the correct procedure, as misapplied payments can complicate the process.
Repayment Options: What Heirs Can Do With the Home
Once the servicer has been notified and the estate is opened, heirs typically have up to six months to resolve the reverse mortgage. This period can often be extended by two additional three-month periods (for a total of up to 12 months) if the estate is making progress toward a sale or refinance. The available options fall into three main categories: repay the loan and keep the home, sell the home and pay off the loan, or walk away and let the lender foreclose (though this last option is rarely advisable).
Option 1: Repay the loan and keep the home. If you or another heir wants to keep the property, you must pay off the reverse mortgage balance. This can be done with personal funds, by refinancing into a new forward mortgage, or by using proceeds from a life insurance policy or other assets. The payoff amount includes the principal balance, accrued interest, and any service fees. Refinancing into a forward mortgage is a common choice for heirs who qualify for a new loan. It converts the reverse mortgage into a traditional mortgage with monthly payments, and any remaining equity stays with the heirs.
Option 2: Sell the home and pay off the loan. Most heirs choose to sell the property. The sale proceeds are used to pay off the reverse mortgage balance, and any remaining equity goes to the estate. If the sale price is less than the loan balance, the non-recourse feature means the lender cannot pursue the heirs for the difference (provided the heirs comply with the servicer's requirements). The home must be sold within the allowed time frame, and the servicer must be kept informed of the listing and sale progress.
Option 3: Deed-in-lieu of foreclosure or short sale. If the home is worth less than the loan balance and cannot be sold in time, heirs may consider a deed-in-lieu of foreclosure, where the property is voluntarily transferred to the lender. This option avoids the stigma and costs of foreclosure and may be a cleaner exit. A short sale, where the lender agrees to accept less than the full balance, is another possibility, though it requires lender approval and can take time.
When comparing these options, it helps to work with a financial advisor or estate attorney who can run the numbers. For heirs who need to explore refinancing or want to compare loan quotes, resources like MortgageZone offer educational tools and lender comparisons that can simplify the decision. The key is to act before the deadline and to document every communication with the servicer.
The Role of the Servicer and Required Notifications
The reverse mortgage servicer is the company that manages the loan on behalf of the lender. They are your primary point of contact throughout the settlement process. Servicers are required by FHA guidelines to provide heirs with clear information about the loan balance, the repayment options, and the deadlines. They must also respond to reasonable requests for payoff statements and provide extensions when warranted.
However, servicers are not advisors. They cannot tell you which option is best for your family, and they are not responsible for protecting your interests. That is why it is crucial to keep meticulous records of all interactions. Send notifications via certified mail with return receipt requested, and follow up with phone calls to confirm receipt. If you request an extension, do so in writing and include evidence of your progress (such as a signed listing agreement or a loan application).
One common pitfall is failing to update the servicer on changes in the estate's status. For example, if you change real estate agents or if the probate process hits a snag, the servicer may interpret the lack of progress as a reason to deny an extension. Proactive communication can prevent misunderstandings and keep the process on track.
Working With an Estate Attorney or Financial Advisor
Reverse mortgage obligations for heirs and estate settlement involve legal and financial complexities that are best navigated with professional help. An estate attorney can review the loan documents, confirm the non-recourse status, and advise on the probate process. They can also help you negotiate with the servicer if disputes arise. A financial advisor can analyze whether keeping the home makes sense given your goals, tax implications, and cash flow needs.
When selecting professionals, look for those with experience in reverse mortgages and elder law. Ask about their fees upfront and clarify what services are included. Some attorneys offer flat-fee packages for estate settlement, while others bill hourly. A good advisor will help you avoid common mistakes, such as missing deadlines, failing to secure the property, or overlooking tax consequences of a sale.
Remember that time is of the essence. The longer you wait to engage professionals, the fewer options you may have. Start by contacting your local bar association for referrals or asking trusted friends and family for recommendations.
Tips for a Smooth Estate Settlement
Beyond the formal steps, a few practical strategies can make the process smoother. First, maintain the property. Even if the home is vacant, keep the utilities on, mow the lawn, and ensure the insurance remains in force. Neglect can lead to code violations or property damage, which may reduce the sale price and complicate the settlement.
Second, keep the estate's finances separate from your own. Open a dedicated estate bank account for expenses related to the home, such as repairs or insurance. This separation simplifies accounting and protects you from personal liability.
Third, be realistic about timelines. Probate can take months, and real estate sales can take even longer. Build buffer time into your plans and request extensions early rather than waiting until the last minute.
Finally, do not sign anything from the servicer without understanding it fully. If a document seems confusing, ask the servicer to explain it or have your attorney review it. Signing a deed-in-lieu or a repayment agreement without proper advice can have long-term consequences.
Settling an estate with a reverse mortgage is a process, not an event. By understanding the non-recourse protection, acting promptly, and leveraging professional guidance, heirs can fulfill their obligations and preserve the family's financial legacy. For more tools and lender comparisons to help you navigate refinancing or selling, explore the resources at RefinancingCo.com.