
Estate Planning Considerations With a Reverse Mortgage
Estate planning considerations with a reverse mortgage start with heirs: learn how non-recourse protection limits liability and how to keep the home.
By Jack Hayes
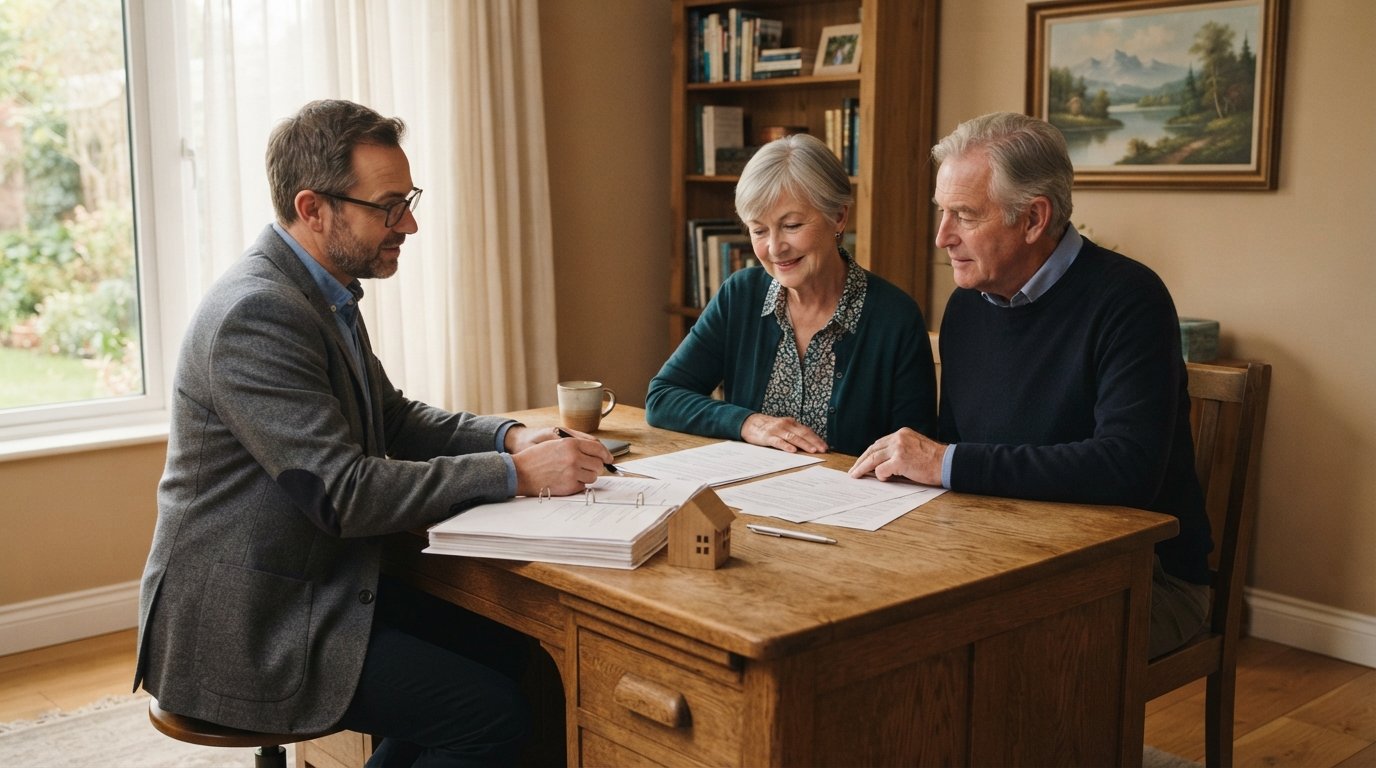
Most people who take out a reverse mortgage do so to stay in their home and supplement retirement income. What many borrowers and their families do not fully plan for is what happens to that home, and the loan attached to it, when the last borrower passes away. Estate planning considerations with a reverse mortgage are not complicated in principle, but they require clear communication, realistic timelines, and a basic understanding of how the loan interacts with wills, trusts, and the heirs who inherit the property. Get these details right and a reverse mortgage can remain a useful financial tool to the very end. Get them wrong and heirs can face confusion, missed deadlines, and unnecessary pressure to sell quickly.
What Happens to a Reverse Mortgage When the Last Borrower Dies
A reverse mortgage is a home loan available to homeowners aged 62 and older. Instead of making monthly mortgage payments, the borrower receives money from the home equity, and the loan balance grows over time as interest and fees accrue. The loan becomes due and payable when the last surviving borrower dies, permanently moves out, or sells the home. For estate planning purposes, the death of the last borrower is the event that matters most.
At that point, the loan servicer must be notified. The estate or the heirs typically have a defined window, generally around 30 days from the borrower's death, to notify the lender and begin the process of resolving the loan. From there, the heirs have several months to either pay off the loan, sell the home, or refinance it into a new mortgage. The exact timelines and requirements are set by the loan terms and federal guidelines, and they can be extended in certain circumstances, but they are not indefinite. Families that delay notification or ignore servicer correspondence often find themselves facing foreclosure proceedings, even when they intend to keep the home.
This is where estate planning considerations with a reverse mortgage start to matter in practical terms. The question is not only who inherits the house, but who is responsible for managing the loan payoff process, who has the authority to communicate with the servicer, and where the money will come from if the heirs want to keep the property. A will that simply says "the house goes to my children" leaves out the operational details that determine whether those children can actually afford to keep it.
Options for Heirs: Repay, Sell, or Refinance
Heirs generally have three paths when a reverse mortgage comes due. Each has different financial implications, and the right choice depends on the home's value, the loan balance, the heirs' resources, and whether anyone actually wants to live in the property. Understanding these options in advance is one of the most important estate planning considerations with a reverse mortgage, because it allows families to make decisions calmly rather than under deadline pressure.
The first option is to pay off the loan and keep the home. Heirs can use their own funds, life insurance proceeds, or other assets to satisfy the balance. This is often the cleanest path when the loan balance is modest relative to the home's value and the heirs want to preserve the property. The second option is to sell the home and use the proceeds to pay off the loan, keeping any remaining equity. This is common when no heir wants to live in the house or when the loan balance is close to the home's value. The third option is to refinance the reverse mortgage into a traditional forward mortgage, which allows an heir to keep the home while spreading payments over time.
Each path has timing and qualification requirements. A refinance, for example, requires the heir to qualify for a new loan based on income, credit, and debt-to-income ratios, which is not always possible for retirees or heirs with limited income. A sale requires coordinating with the servicer and possibly paying off the loan at closing. Paying off the loan outright requires liquid assets. Families that discuss these options ahead of time, ideally with the borrower involved, are far better positioned to act quickly when the time comes. If you are still exploring how the loan itself works, our guide on how a reverse mortgage works for seniors explains the mechanics in plain language.
Non-Recourse Protection and What It Means for Heirs
Most reverse mortgages are non-recourse loans. That means the lender cannot pursue the borrower or the borrower's estate for more than the home is worth. If the loan balance exceeds the home's value when the loan comes due, the heirs are not personally liable for the shortfall, and the estate is not required to cover the difference. The lender's recovery is generally limited to the proceeds from the sale of the property.
This protection is one of the most important features of a reverse mortgage, and it is frequently misunderstood. Heirs sometimes assume they are on the hook for the full loan balance, which can lead to panic selling or unnecessary financial strain. In reality, the non-recourse rule means that if the home is worth less than the loan balance, the heirs can typically walk away without owing anything further, provided they follow the proper process. The lender may pursue a claim against the estate in limited circumstances, such as fraud or failure to maintain the property, but the basic structure protects heirs from inheriting a debt that exceeds the home's value.
There is a caveat worth planning for: the non-recourse protection applies to the loan itself, but it does not eliminate the need to maintain the property, pay property taxes, and keep homeowners insurance current while the loan is outstanding. If the borrower fails to meet these obligations, the loan can become due earlier than expected, which complicates estate planning. Families should build these ongoing costs into the borrower's budget and, if possible, set aside reserves for maintenance and taxes. Estate planning considerations with a reverse mortgage are not only about the payoff event; they also include the years of stewardship that precede it.
Coordinating a Reverse Mortgage With Wills, Trusts, and Family Discussions
A reverse mortgage does not automatically transfer with a will in the way many people assume. The loan is a lien on the property, and the heirs' ability to inherit the home depends on how the estate is structured and how the loan is resolved. A will can name who should receive the home, but it cannot override the lender's right to be paid. A trust can hold the home and provide a framework for managing the loan payoff, but the trustee must have the authority and the resources to act. In either case, the estate plan should explicitly address the reverse mortgage, the servicer contact information, and the intended strategy for repayment or sale.
Family discussions are equally important. Heirs who learn about a reverse mortgage only after the borrower's death are at a disadvantage. They may not know the loan balance, the servicer's name, or whether the borrower intended for the home to be kept or sold. A simple family meeting, or a letter of instruction stored with the estate documents, can prevent months of confusion. The following steps can help families coordinate a reverse mortgage with the rest of the estate plan:
- Document the loan details, including the servicer, loan balance, and any set-aside accounts for taxes and insurance.
- Name a point person, such as an executor or trustee, who is authorized to communicate with the servicer.
- Discuss the heirs' intentions for the home and confirm whether anyone is prepared to refinance or pay off the loan.
- Review the estate plan with an attorney who understands reverse mortgages and can align the will or trust with the loan terms.
- Keep a reserve fund or life insurance policy that can be used to pay off the loan if keeping the home is the goal.
These steps do not require a complicated legal structure. They require clarity. A reverse mortgage is a financial tool, and like any tool, it works best when the people who will eventually manage it understand how it operates. The borrower's attorney, financial advisor, and family members should all be working from the same information.
Common Estate Planning Mistakes With Reverse Mortgages
The most common mistake is failing to notify the servicer promptly after the borrower's death. Heirs sometimes assume the loan will simply wait until they are ready, but servicers operate on timelines and are required to protect the lender's interest. Missing deadlines can lead to foreclosure, which eliminates the heirs' options and can result in the loss of remaining equity. Another common mistake is assuming the home can be inherited without resolving the loan. The deed may transfer, but the lien remains, and the lender can still foreclose if the loan is not paid or refinanced.
A third mistake is failing to plan for the cost of keeping the home. Even if the heirs want to keep the property, they need to be able to pay off the reverse mortgage, which may require a new loan, cash, or a sale of other assets. Families that assume the home is "free and clear" because the borrower had no monthly mortgage payment are often surprised to learn how much the loan balance has grown. Interest and fees accrue over time, and the balance can be substantial after several years. Estate planning considerations with a reverse mortgage should include a realistic estimate of the payoff amount and a plan for covering it.
Finally, some families fail to coordinate the reverse mortgage with the rest of the estate. If the home is the largest asset and the reverse mortgage consumes most of its value, the heirs may receive little or nothing from the property. That is not necessarily a problem, but it should be planned for. The borrower may want to use other assets, such as life insurance or savings, to balance the inheritance among heirs. An estate planning attorney can help structure these arrangements so that the borrower's intentions are clear and the heirs are treated fairly.
Where to Get Help and Compare Options
Estate planning considerations with a reverse mortgage are best addressed before the loan is taken out, but it is never too late to organize the details. Borrowers who are still shopping for a reverse mortgage should compare offers from multiple lenders, review the loan terms carefully, and ask specifically about the servicer's process for handling the loan after death. Families who are already managing a reverse mortgage can contact the servicer for a payoff statement and timelines, and they can consult an attorney or financial advisor for guidance on the best path forward.
For borrowers and families who want to compare reverse mortgage options or explore related loan products, resources such as MortgageZone provide educational content and tools that can help clarify the process. RefinancingCo.com also connects homeowners with participating lenders who can provide quotes for reverse mortgages and other loan types, allowing families to review options side by side before making a decision. Comparing offers is not just about the interest rate; it is also about understanding how each lender handles loan servicing, payoff requests, and heir communication, all of which affect the estate planning side of the equation.
The bottom line is that a reverse mortgage does not have to complicate an estate. With clear documentation, honest family conversations, and a basic understanding of the payoff process, heirs can step into a manageable situation rather than a crisis. The borrowers who plan ahead, and the families who understand the loan before it comes due, are the ones who preserve the most options and the most equity. Estate planning considerations with a reverse mortgage are ultimately about communication and preparation, and both are entirely within a family's control.