
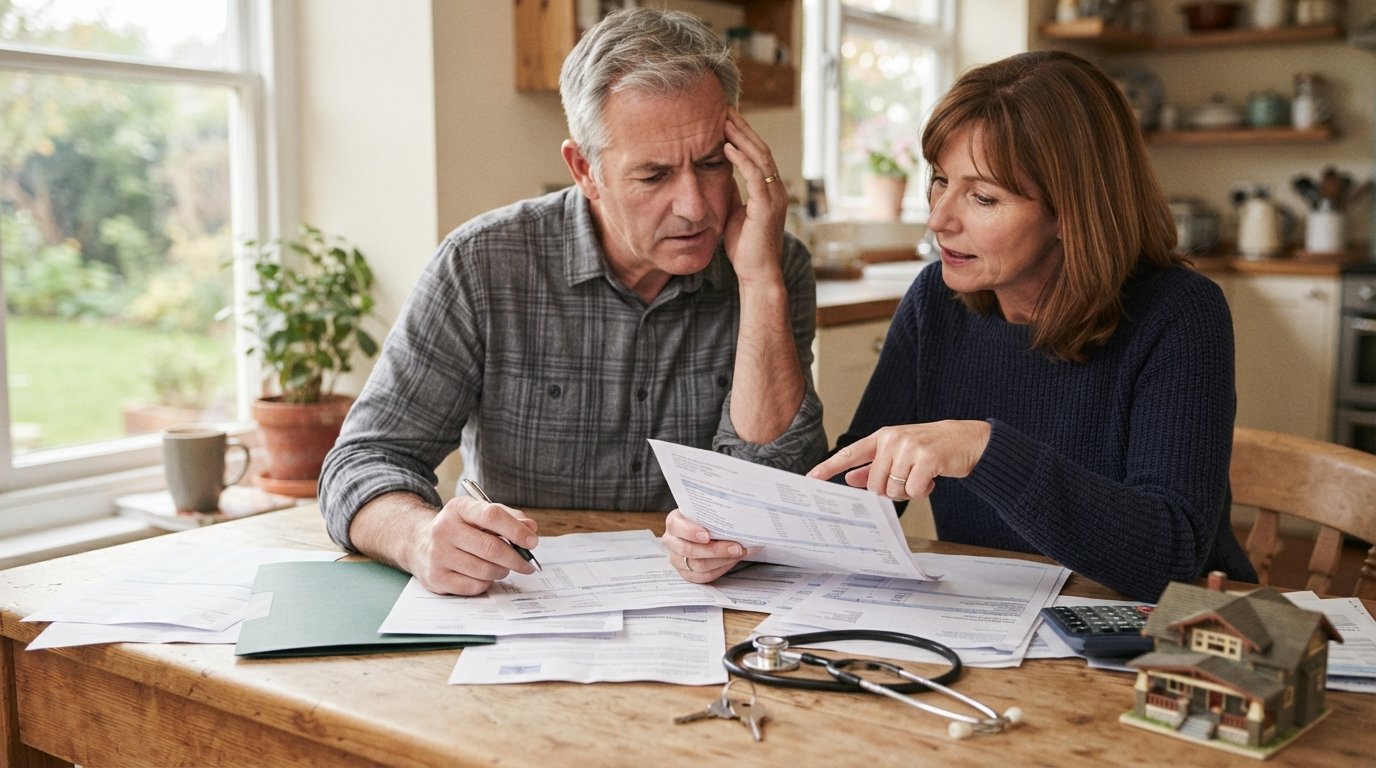
Using Home Equity for Medical Expenses: Pros and Cons
Using home equity for medical expenses pros and cons: lower rates and flexible funds, but foreclosure risk and lost equity demand careful comparison first.
By Sophie Adler
A medical crisis can arrive without warning, and the bills that follow often dwarf even the most carefully built savings account. When a hospital stay, surgery, or ongoing treatment leaves you facing tens of thousands of dollars in costs, the equity locked inside your home can look like a lifeline. It is a real option, and for many homeowners it is the difference between financial stability and financial collapse. But using home equity for medical expenses carries genuine trade-offs, and understanding the pros and cons before you sign anything is essential. This guide walks through the mechanics, the risks, the tax questions, and the alternatives so you can make a decision that protects both your health and your home.
How Home Equity Can Pay for Medical Bills
Home equity is the difference between what your house is worth and what you still owe on your mortgage. If your home appraises at $400,000 and you owe $250,000, you have $150,000 in equity. Lenders generally let you borrow against a portion of that figure, often up to 80 or 85 percent of your home's value combined with your first mortgage. For a household facing major medical expenses, that accessible cash can be substantial.
There are three primary ways to convert home equity into medical expense funding, and each works differently. A home equity loan gives you a lump sum at a fixed interest rate, repaid over a set term, which makes budgeting predictable. A home equity line of credit, or HELOC, works more like a credit card tied to your house: you draw what you need, when you need it, during a draw period, and you pay interest only on the outstanding balance. A cash-out refinance replaces your existing mortgage with a larger one and hands you the difference in cash, which can be useful if you also want to lower your rate or change your loan term at the same time.
Choosing among them depends on the shape of your medical expenses. A one-time surgery with a known price tag fits a home equity loan well. Ongoing treatment with unpredictable monthly costs, such as chemotherapy or dialysis, often suits a HELOC because you can draw funds as bills arrive. A cash-out refinance makes the most sense when your current mortgage rate is higher than today's market and you want to restructure your entire debt picture. For a deeper look at how these tools compare across different funding scenarios, our guide on using home equity for college tuition walks through the same trade-offs in an educational context.
Before applying anywhere, it helps to compare offers from multiple lenders. RefinancingCo.com connects homeowners with participating lenders who provide quotes for home equity loans, HELOCs, and cash-out refinances, and comparing those quotes side by side is one of the simplest ways to avoid overpaying on interest. The platform is not a lender and does not set rates, but it does streamline the process of seeing what network members are willing to offer.
The Pros: Why Home Equity Can Be a Smart Medical Funding Tool
The most immediate advantage is cost. Credit card interest rates often sit above 20 percent, and medical credit cards and personal loans can carry similarly steep pricing. Home equity products are secured by your property, which means lenders can offer much lower rates, frequently in the single digits for well-qualified borrowers. On a $30,000 medical bill repaid over five years, the difference between a 22 percent credit card and an 8 percent home equity loan can exceed $10,000 in saved interest. That is real money that stays in your pocket during a financially stressful period.
Home equity also offers longer repayment terms than most unsecured alternatives. Medical credit cards often require full repayment within a promotional window or convert to punishing deferred interest. A home equity loan can stretch across 10, 15, or even 20 years, which lowers the monthly payment and keeps cash flow manageable while you recover or manage a chronic condition. For families facing a long treatment roadmap, that breathing room matters.
Another point in favor is that the funds can be used for anything. Unlike a mortgage that must go toward a home purchase, home equity proceeds carry no usage restrictions. You can pay hospital invoices, cover prescription costs, fund home modifications for accessibility, or pay for travel to a specialist. That flexibility is valuable when medical expenses arrive from multiple directions at once. Here is a quick summary of the core advantages:
- Lower interest rates than credit cards or personal loans because the debt is secured
- Longer repayment terms that reduce monthly payment pressure
- Flexible use of funds with no restrictions on how the money is spent
- Potential tax benefits in certain circumstances (discussed below)
- Access to large sums that may exceed unsecured lending limits
Finally, using home equity keeps your other assets intact. You do not have to liquidate retirement accounts, sell investments at a loss, or drain an emergency fund that might be needed for the next crisis. For homeowners with significant equity but limited liquid cash, this can be the least disruptive way to cover a large medical bill.
The Cons: Risks You Must Weigh Carefully
The biggest risk is foreclosure. Home equity loans and HELOCs are secured by your house, which means that if you fall behind on payments, the lender can ultimately take the property. Medical crises often come with income disruption, whether from missed work, reduced hours, or a disability that ends a career. Taking on a new secured debt during a period of uncertain income is a serious decision, and it deserves honest scrutiny. If there is a realistic chance you will struggle to make the new payment, a secured loan may convert a medical problem into a housing problem.
There is also the issue of lost equity. Your home is likely your largest asset and a key part of your long-term financial security. Every dollar you borrow against it reduces the cushion you have built and increases the amount you owe. If home values decline after you borrow, you could find yourself underwater, owing more than the house is worth. That scenario limits your ability to sell, refinance, or move when circumstances change. Borrowing against equity for a one-time medical need is one thing; repeatedly tapping the house for recurring expenses can erode a lifetime of savings.
Closing costs and fees add another layer of cost that borrowers often overlook. Home equity loans and cash-out refinances typically carry appraisal fees, origination charges, title searches, and recording fees that can run into the thousands. A HELOC may have annual fees, early closure penalties, or a variable rate that rises over time. These costs reduce the effective benefit of the lower interest rate and should be factored into any comparison. The Consumer Financial Protection Bureau and housing counselors regularly warn that these products are not free money, and the fine print deserves a careful read.
Finally, there is a behavioral risk. Once a HELOC is open, the available credit can feel like a safety net, and it is easy to draw on it for non-medical expenses. Homeowners who use equity for medical bills should have a clear repayment plan and resist the temptation to treat the line of credit as general spending money. Discipline is what separates a smart use of equity from a dangerous one.
Tax Considerations: Medical Deductions and Mortgage Interest
Tax rules around medical expenses and home equity are frequently misunderstood, so it pays to separate the two issues. On the medical side, the IRS allows taxpayers to deduct qualified medical expenses that exceed a percentage of adjusted gross income, currently 7.5 percent for most filers. That deduction applies to the medical costs themselves, not to the loan you used to pay them. In other words, borrowing against your home does not create a new medical deduction; it simply provides the cash to pay bills that may already be deductible if you itemize and exceed the threshold.
On the mortgage side, the Tax Cuts and Jobs Act changed how home equity debt interest is treated. For tax years through 2025, interest on home equity loans and lines of credit is generally deductible only when the funds are used to buy, build, or substantially improve the home that secures the loan. Using a home equity loan to pay medical bills typically does not qualify for the mortgage interest deduction, even though the loan is secured by your house. Cash-out refinance interest follows similar rules: the portion of the new loan that exceeds your original mortgage balance is generally deductible only if used for home improvement. Because tax law can change and individual circumstances vary, confirm your specific situation with a qualified tax professional before assuming any deduction.
There is one more angle worth knowing. Some medical expenses, such as certain home modifications prescribed by a doctor, may qualify as deductible medical expenses, and in limited cases improvements made for medical reasons can affect the basis of your home. These are narrow exceptions, but they illustrate why documentation matters. Keep receipts, invoices, and medical records organized so that if a deduction is available, you can substantiate it.
Alternatives to Consider Before Tapping Home Equity
Home equity is not the only path, and for some households it is not the best one. Before committing, work through the alternatives systematically. Hospital financial assistance programs are often overlooked: nonprofit hospitals are required to offer charity care and discounted payment plans, and a simple conversation with the billing department can reduce a bill by thousands. Negotiating a self-pay discount or an interest-free installment plan directly with the provider costs nothing and preserves your home equity.
Personal loans and medical credit cards are unsecured, meaning they do not put your house at risk, though their interest rates are higher. For smaller balances that can be repaid quickly, the extra interest may be a fair price for avoiding foreclosure risk. Retirement accounts are another option, but borrowing from a 401(k) or withdrawing from an IRA carries its own penalties and long-term costs, so these should be approached with caution. Health savings accounts and flexible spending accounts, if you have them, offer tax-advantaged ways to pay for qualified expenses.
For homeowners aged 62 and older, a reverse mortgage is a distinct option worth exploring. It allows you to convert home equity into cash without making monthly mortgage payments, and the loan is repaid when the home is sold or the borrower permanently leaves. Reverse mortgages can be structured as a lump sum, monthly installments, or a line of credit, and they are sometimes used specifically to cover medical and long-term care costs. RefinancingCo.com provides educational resources and quote comparisons for reverse mortgages through its network of participating lenders, which can help older homeowners evaluate whether this route fits their situation better than a traditional home equity loan.
Here is a practical sequence to follow before you borrow:
- Ask the hospital or provider for financial assistance, charity care, or a discounted payment plan.
- Check whether you qualify for Medicaid, disability benefits, or other public programs.
- Compare unsecured options such as personal loans and medical credit cards for smaller balances.
- Review retirement and health savings account options with a tax professional.
- Only then evaluate home equity products and compare quotes from multiple lenders.
Working through this list takes time, but it can save you from borrowing more than necessary or taking on risk you do not need. For readers who want a broader grounding in how mortgage products work before making a decision, resources such as MortgageZone offer plain-language explanations of loan structures, calculators, and lender comparisons that complement the quote process.
How to Compare Home Equity Offers for Medical Bills
If home equity is the right fit, the next step is shopping carefully. Start by pulling your credit reports and checking your score, since pricing tiers depend heavily on creditworthiness. Gather documentation of your income and medical expenses, and decide whether you need a fixed lump sum or a flexible line of credit. Then request quotes from at least three lenders, including banks, credit unions, and online marketplace participants, and compare them on the same basis: annual percentage rate, fees, repayment term, and whether the rate is fixed or variable.
Pay attention to the details that do not show up in the headline rate. A HELOC with a low introductory rate may reset sharply after the promotional period. A home equity loan with no closing costs may carry a higher interest rate to compensate. A cash-out refinance may extend your repayment timeline and increase total interest even as it lowers your monthly payment. Ask each lender for a Loan Estimate, which standardizes the numbers and makes side-by-side comparison possible.
RefinancingCo.com is built for exactly this stage of the process. The platform lets homeowners request quotes for home equity loans, HELOCs, cash-out refinances, and reverse mortgages from participating network members, with no obligation to accept an offer. Because RefinancingCo.com is not a lender and does not originate or fund loans, the rates and terms you see come directly from the lenders in the network, and comparing several of them is the most reliable way to find a competitive deal. Submitting a request takes only a few minutes and can reveal options you would not find by calling a single bank.
As you review offers, keep your total debt-to-income ratio in mind. Lenders will evaluate whether you can comfortably carry the new payment alongside your existing mortgage and other obligations. If the numbers are tight, a smaller HELOC or a shorter-term home equity loan may be safer than borrowing the maximum available. The goal is to solve the medical bill problem without creating a new one.
Making the Decision with Clear Eyes
Using home equity for medical expenses can be a sensible, even lifesaving, financial move when the numbers work and the risks are understood. The lower interest rates, longer terms, and flexible use of funds make it one of the most powerful tools available to homeowners facing large health care bills. At the same time, the foreclosure risk, loss of equity, closing costs, and tax limitations mean it is not a decision to make in haste or under pressure.
The homeowners who navigate this best are the ones who exhaust cheaper alternatives first, borrow only what they need, choose the product that matches the shape of their expenses, and compare quotes from multiple lenders before signing. They also keep a repayment plan in view from day one, so that a medical crisis does not quietly become a housing crisis years later. If you are considering this route, start with a clear picture of your equity, your expenses, and your income stability, then let competition among lenders work in your favor.