Reverse Mortgage Payment Options: Lump Sum, Monthly, Line of Credit
Compare reverse mortgage payment options lump sum monthly line of credit. Call (833)-997-2850 to find the payout structure that fits your needs.
By Andrew Nguyen
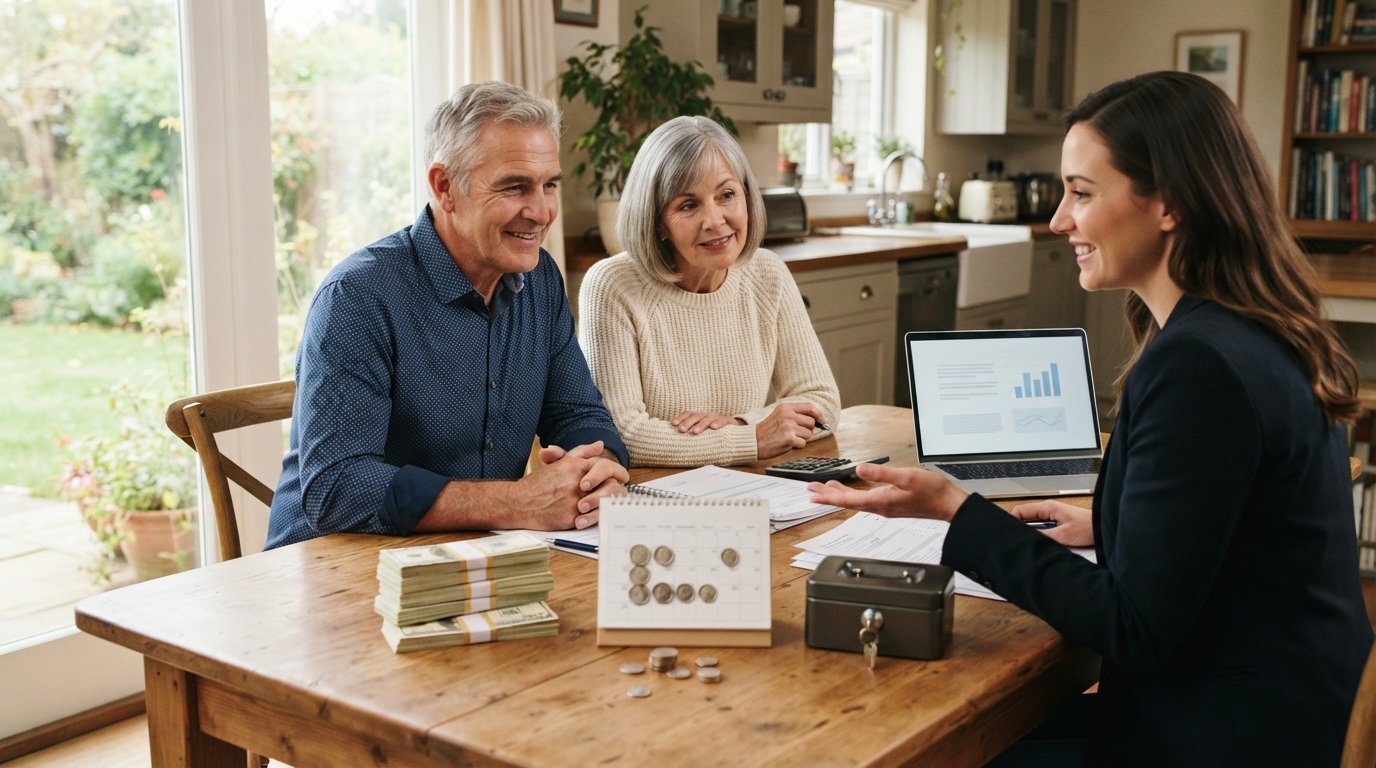
A reverse mortgage can turn home equity into cash, but the way you receive that cash matters as much as the loan itself. Choose a lump sum and you get immediate access to a large pool of money. Choose monthly payments and you create a predictable income stream. Choose a line of credit and you have a flexible reserve you can tap only when needed. Each reverse mortgage payment option, lump sum, monthly, and line of credit, serves a different financial purpose, and the right choice depends on your expenses, income sources, and how much uncertainty you want to manage.
This guide breaks down how each payout structure works, who it tends to suit, and what to watch for. It also explains how to compare offers from multiple lenders so you can align the payment option with your actual retirement cash flow. If you are weighing a reverse mortgage against other ways to access home equity, understanding these options is the first step toward a decision you will not regret.
How Reverse Mortgage Payouts Work
A reverse mortgage, most commonly a Home Equity Conversion Mortgage (HECM) backed by the Federal Housing Administration, lets homeowners aged 62 and older convert part of their home equity into loan proceeds. Unlike a traditional mortgage, you are not required to make monthly principal and interest payments. The loan becomes due when the last borrower permanently leaves the home, sells it, or fails to meet loan obligations such as paying property taxes and homeowners insurance.
The amount you can access depends on your age (or the age of the youngest borrower), the appraised home value, current interest rates, and the lending limit for your area. After mandatory obligations are settled, such as paying off an existing mortgage or liens, the remaining funds can be distributed in several ways. The three core choices are a lump sum, monthly installments, and a line of credit. Some borrowers combine them, for example, taking a partial lump sum to cover an immediate expense and keeping the rest in a growing line of credit.
It helps to think of the payout decision as a cash-flow design problem. You are matching a finite resource (your home equity) to an uncertain timeline (your lifespan and future expenses). The right structure should give you enough liquidity for near-term needs while preserving flexibility for later. Availability of specific options can vary by lender and program, so comparing offers from participating lenders is essential before you commit.
Lump Sum Payout: Immediate Access to Cash
A lump sum payout delivers the available loan proceeds in one disbursement at closing. This is the simplest structure to understand and often the most appealing when you have a large, immediate financial need. Common uses include paying off high-interest debt, funding a major home repair or accessibility renovation, covering medical expenses, or helping family members with a down payment. The appeal is obvious: you get the money now, and you can deploy it however you choose.
However, a lump sum comes with tradeoffs. Because the entire amount is drawn at once, interest begins accruing on the full balance immediately. That can erode your equity faster than a structure where funds are drawn over time. A lump sum also eliminates the future flexibility that a line of credit provides. If you take everything upfront and later face an unexpected expense, you may have no remaining reverse mortgage funds to draw on. For borrowers with a clear, one-time need and no desire for ongoing access, a lump sum can be a clean solution. For those who want a safety net, it may be too rigid.
When a Lump Sum Makes Sense
A lump sum tends to fit borrowers who have a defined expense that cannot be handled gradually. Examples include a roof replacement, a medical procedure not fully covered by insurance, or consolidating credit card balances to reduce monthly interest costs. It can also work for someone who wants to simplify their finances by eliminating an existing mortgage payment entirely and does not anticipate needing additional cash from the home later.
Before choosing a lump sum, calculate the total interest cost over your expected time in the home. Because interest compounds on the full drawn amount, the long-term cost can be higher than with a line of credit or monthly payments. Ask your lender for a side-by-side comparison of projected loan balances under each option. That comparison can reveal whether the convenience of a lump sum is worth the extra cost.
Monthly Installments: A Predictable Income Stream
Monthly installments convert your available loan proceeds into a regular payment, either for a fixed term (such as 10 years) or for as long as you live in the home (a tenure payment). This structure essentially creates a private pension backed by your home equity. For many retirees, the biggest risk is outliving their savings, and a tenure payment directly addresses that risk by guaranteeing income for life as long as the loan obligations are met.
Monthly payments are particularly useful for covering recurring expenses: groceries, utilities, insurance premiums, property taxes, and routine healthcare costs. They can supplement Social Security or a pension and reduce the need to sell investments during market downturns. The predictable cadence also makes budgeting easier. You know how much will arrive each month and can plan accordingly.
Fixed-Term vs. Tenure Payments
A fixed-term payment plan distributes the proceeds over a set number of months, which you choose at closing. This can be useful if you have a known period of higher expenses, such as the years before you claim Social Security at age 70. A tenure payment, by contrast, continues for as long as you live in the home, regardless of how long that is. Tenure payments typically result in smaller monthly amounts than a short fixed-term plan because the lender must plan for a longer payout period.
One consideration with monthly installments is that you cannot easily access a large sum later if an emergency arises. Some lenders allow you to combine a monthly payment with a line of credit for exactly this reason. If you choose a monthly plan, ask whether a partial line of credit can be added as a buffer. Also confirm how the payments are treated for tax and benefit purposes, since reverse mortgage proceeds are generally tax-free loan advances but can affect needs-based benefits like Medicaid in some situations.
Line of Credit: Flexible Access When You Need It
A line of credit lets you draw funds as needed, up to your available limit, and you only accrue interest on the amount you actually borrow. This is the most flexible of the three options. You can leave the line untouched for years and draw a large amount only when a specific need arises, such as a home repair, a medical bill, or a period of unexpected unemployment. For borrowers who value optionality and want a safety net, a line of credit is often the best fit.
Most HECM lines of credit include a growth feature: the unused portion of the line increases over time at a rate tied to the loan's interest rate. That means your available credit can grow even if your home value does not appreciate. This growth can provide a larger reserve in later years, which is valuable if you are using the line as a long-term contingency fund. The tradeoff is that variable-rate lines can have adjustable interest rates, so the cost of drawing funds may change over time.
Strategies for Using a Line of Credit
One common strategy is to open the line of credit and leave it mostly untouched, using it only for emergencies or planned expenses. This preserves your equity and lets the available credit grow. Another approach is to use the line for a series of smaller draws over time, such as funding home modifications as mobility needs change. Some borrowers pair a line of credit with a monthly payment, using the monthly payment for routine income and the line for irregular expenses.
Keep in mind that a line of credit requires discipline. Because the funds are available, there is a temptation to draw on them for discretionary spending. Treat the line as a reserve, not a checking account. Also review the terms carefully: some lines have annual fees, and the interest rate may be adjustable. Comparing offers from multiple lenders can help you find a line with favorable terms and a structure that matches your spending patterns.
Which Reverse Mortgage Payment Option Fits Your Situation?
There is no universally correct payout choice. The right answer depends on your income sources, your health and life expectancy, your expense patterns, and your tolerance for risk. A retiree with a stable pension and a one-time home repair need might prefer a lump sum. Someone who relies primarily on Social Security and wants predictable monthly income may favor tenure payments. A homeowner who wants a flexible emergency fund and expects to stay in the home for many years may find a line of credit most useful.
It is also possible to combine options. Many lenders allow you to take a partial lump sum at closing, receive monthly payments for a set period, and keep the remaining funds in a line of credit. This blended approach can address multiple needs at once: immediate cash for a specific expense, ongoing income for a few years, and a reserve for the future. The key is to model your cash flow under each scenario and see which structure leaves you feeling most secure.
When comparing reverse mortgage payment options, lump sum, monthly, and line of credit, ask each lender for projections of your loan balance over time under each choice. Look at the total cost, the remaining equity, and the flexibility you retain. Consider how each option would perform if you live longer than expected, if home values decline, or if you face a large unexpected expense. A structure that feels comfortable in good times should also be stress-tested against less favorable scenarios.
Comparing Lenders and Getting Personalized Quotes
Reverse mortgage terms, fees, and available payout options can vary significantly from one lender to another. The same borrower might qualify for different line sizes, different monthly payment amounts, or different combinations of options depending on the lender's pricing and underwriting. That is why shopping around is essential. A single quote does not tell you whether you are getting a competitive deal.
Start by gathering quotes from at least three lenders that offer reverse mortgages in your state. Ask each lender to provide a breakdown of closing costs, the projected loan balance over 5, 10, and 20 years under each payout option, and any servicing fees. Compare not just the interest rate but the total cost of the loan. Also ask about the lender's reputation and customer service, since reverse mortgages are long-term relationships.
If you want a streamlined way to compare offers from participating lenders, you can use a mortgage comparison platform to request quotes and review options side by side. For broader mortgage education and tools, resources like MortgageZone can help you understand the broader lending landscape. And if you are still in the early stages of learning how reverse mortgages work, our guide on how a reverse mortgage works for seniors explains the eligibility rules, obligations, and repayment process in plain language.
Key Takeaways and Next Steps
- Lump sum: Best for a one-time, large expense; costs more in interest over time because the full balance accrues immediately.
- Monthly installments: Best for predictable income needs; choose tenure for lifetime payments or fixed-term for a set period.
- Line of credit: Best for flexibility and emergency reserves; unused credit may grow over time, but variable rates apply.
- Combination: Many borrowers blend options to cover immediate needs, ongoing income, and future contingencies.
- Compare lenders: Terms and available options vary, so request quotes from multiple participating lenders before deciding.
Before you commit, consider your long-term plans. Will you stay in the home for many years, or might you downsize? Do you have other assets you can tap in an emergency, or is home equity your primary reserve? How would a market downturn or a health event affect your ability to pay property taxes and insurance, which are required to keep the loan in good standing? Answering these questions will help you choose a payout structure that supports your overall retirement strategy, not just your immediate cash needs.
Finally, remember that a reverse mortgage is a significant financial decision with long-term consequences. Take your time, ask questions, and use the comparison tools available to you. With the right payment option and a lender that fits your needs, a reverse mortgage can provide meaningful financial flexibility in retirement. If you are ready to explore reverse mortgage payment options, lump sum, monthly, line of credit, and more, start by requesting personalized quotes from participating lenders through RefinancingCo.com.