Documents Needed for Mortgage Application Checklist
Gather documents needed for mortgage application checklist with our printable guide. Call (833)-997-2850 for expert assistance.
By Andrew Nguyen
Gathering the right paperwork before you apply for a mortgage can mean the difference between a smooth approval and a frustrating delay. Lenders need a clear picture of your income, assets, and credit history to assess risk, and missing documents are one of the most common reasons applications stall. Whether you are buying your first home, refinancing, or tapping into home equity, having a complete document package ready upfront signals to lenders that you are organized and serious, which can speed up the process and even strengthen your negotiating position. This guide breaks down the documents needed for a mortgage application checklist by category, explains special situations like self-employment, and offers a printable checklist you can use to stay on track.
Why a Complete Document Package Matters
Mortgage underwriting is essentially a verification process. Lenders want to confirm that the information you provide on your application is accurate and that you have the financial capacity to repay the loan. When documents are missing or inconsistent, underwriters must request additional items, which adds days or even weeks to your timeline. In competitive markets, a delay can cost you a home. Moreover, a well-organized document package reduces the back-and-forth with your loan officer and helps you avoid last-minute scrambles.
Beyond speed, completeness can affect your loan terms. Some lenders offer rate locks for a specific period, and if your application drags on due to missing paperwork, you might need to extend the lock, potentially at a higher rate. Having everything ready also makes it easier to compare offers from multiple lenders because you can quickly submit a full application to each one. At MortgageZone, you can find educational resources and tools to help you understand the process, but the responsibility for gathering documents falls on you. Use this checklist to prepare in advance and keep your application moving.
Core Documents Needed for a Mortgage Application Checklist
Most lenders require a standard set of documents from all borrowers, regardless of loan type. These items establish your identity, income, assets, and debts. While specific requirements can vary by lender and loan program, the following categories cover the basics. Use this as your master list and add any additional items your lender requests.
Identity and Personal Information
Lenders must verify that you are who you say you are. You will typically need to provide government-issued photo identification for each borrower, such as a driver's license or passport. Additionally, you may need to supply your Social Security number and proof of residence, which could be a utility bill or a lease agreement. Some lenders also request a copy of your Social Security card. If you have changed your name, provide documentation such as a marriage certificate or court order.
Income Documentation
Income is the cornerstone of mortgage qualification. Lenders want to see a stable, reliable stream of earnings. For salaried employees, the standard requirements include recent pay stubs covering the last 30 days, W-2 forms for the past two years, and possibly a verification of employment. If you receive bonuses, commissions, or overtime, be prepared to show a history of those payments. For hourly workers, pay stubs should reflect consistent hours. If you have changed jobs recently, a offer letter or contract may be requested.
Asset Documentation
Lenders need to verify that you have funds for a down payment and closing costs, as well as reserves. You will typically provide statements for all checking and savings accounts, investment accounts, and retirement accounts for the past two to three months. Be ready to explain any large deposits that are not from your regular paycheck, as lenders may ask for documentation to confirm the source. Gift funds for a down payment require a gift letter and evidence of transfer.
Debt and Credit Information
Your credit report will be pulled by the lender, but you may need to provide explanations for any derogatory items, such as late payments or collections. If you have student loans, provide statements showing the balance and monthly payment. For other debts like car loans or credit cards, the lender will obtain information from your credit report, but you should be prepared to discuss any large monthly obligations.
Property Documentation
If you are purchasing a home, you will need a copy of the purchase contract once it is executed. For refinancing, provide your current mortgage statement and homeowner's insurance policy. If you are using gift funds, include the gift letter. For condominiums, the lender may require HOA certification and insurance details. Self-employed borrowers or those with rental income should provide leases or property tax statements.
Special Documentation for Self-Employed and Variable-Income Borrowers
If you are self-employed, a freelancer, or have income that varies (such as seasonal work or commissions), lenders will require additional documentation to assess the stability of your earnings. Typically, you will need to provide two years of personal and business tax returns, including all schedules and K-1s. A year-to-date profit and loss statement and a balance sheet may also be requested. Lenders often want to see a two-year history of self-employment and may average your income over that period. If you receive rental income, provide leases and tax returns showing the income. For retirees, Social Security award letters, pension statements, and tax returns suffice. In all cases, be prepared to explain any fluctuations and provide supporting evidence.
How Requirements Vary by Lender and Loan Type
While the core documents are similar across lenders, specific requirements can differ based on the loan program. For example, FHA loans may require additional documentation for gift funds and may have more lenient credit score requirements but stricter property standards. VA loans require a Certificate of Eligibility and may have different income verification rules. USDA loans have income limits and property eligibility requirements. Conventional loans may have stricter reserve requirements. Additionally, some lenders may accept alternative documentation, such as bank statements in lieu of tax returns for certain borrowers. Always confirm the exact document list with your chosen lender or broker. When you compare offers through RefinancingCo.com, you can ask each participating lender about their specific documentation needs, ensuring you are not caught off guard.
Printable Mortgage Application Checklist
Use the following checklist to organize your documents. Print it out and check off each item as you gather it. Keep digital copies as well, as many lenders accept secure uploads.
- Identity and Personal Information: Government-issued photo ID for each borrower, Social Security number, proof of residence (utility bill or lease), name change documentation if applicable.
- Income Documents: Recent pay stubs (last 30 days), W-2 forms (past two years), verification of employment (if requested), bonus/commission/overtime history, offer letter or contract if recently changed jobs.
- Asset Documents: Bank statements (checking and savings, past 2-3 months), investment account statements, retirement account statements, gift letter and proof of transfer for down payment gifts, explanation for large deposits.
- Debt Information: Student loan statements, explanations for derogatory credit items, documentation for other monthly obligations.
- Property Documents (if applicable): Purchase contract, current mortgage statement (for refinance), homeowner's insurance policy, HOA certification and insurance (for condos), lease agreements for rental income.
- Self-Employed/Variable Income: Two years of personal and business tax returns, year-to-date profit and loss statement, balance sheet, K-1s, business license.
- Retirees: Social Security award letters, pension statements, tax returns.
Keep this checklist handy and review it before you start your application. Gathering documents in advance can save you time and reduce stress. Remember that lenders may request additional items during underwriting, so stay responsive and provide any follow-up documentation promptly.
Tips to Organize Your Documents Efficiently
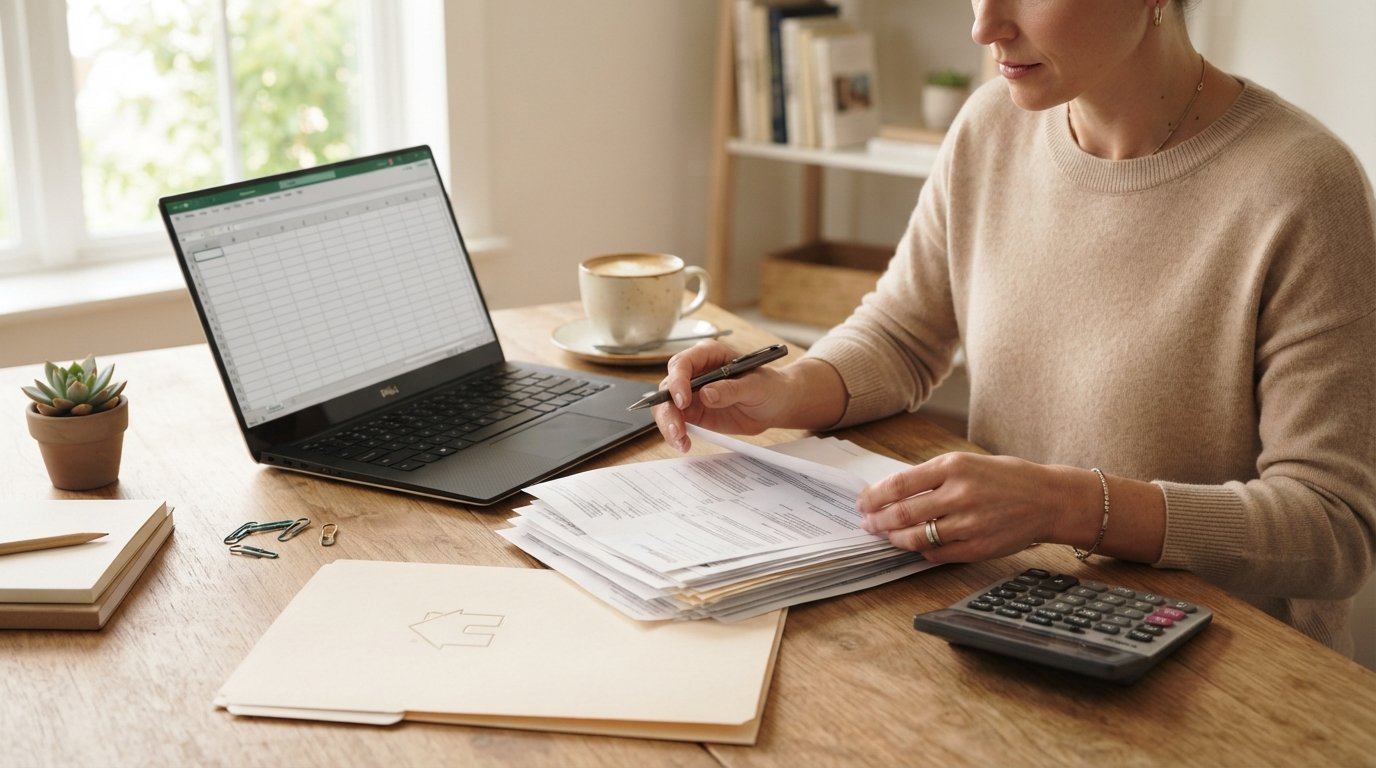
Start by creating a folder, either physical or digital, for your mortgage documents. Label subfolders by category: identity, income, assets, debts, and property. Scan paper documents and save them as PDFs with clear file names, such as "2024_W2_JohnDoe.pdf." This makes it easy to upload when requested. Keep a master list of what you have submitted and what is pending. If you are working with multiple lenders, maintain separate folders for each application. Communication is key: ask your loan officer for a complete document list at the outset and clarify any items that are unclear. Finally, review your documents for consistency, ensuring that names, addresses, and numbers match across all paperwork.
By following this guide and using the checklist, you will be well prepared to submit a complete mortgage application. A little upfront effort can lead to a faster approval and a smoother path to your financial goals.